
By Nana Musa
Nigeria has begun training 100 experts drawn from key government institutions to strengthen the country’s preparedness for its third-round mutual evaluation on anti-money laundering, counter-financing of terrorism and counter-proliferation financing (AML/CFT/CPF).
The five-day capacity-building programme, facilitated by the Inter-Governmental Action Group against Money Laundering in West Africa (GIABA), with support from SecFIN Africa, is holding in Abuja from October 12 to 16, 2026.
The training is designed to establish a common understanding of the mutual evaluation methodology and prepare members of Nigeria’s Mutual Evaluation Working Groups (MEWG) for a national mock assessment scheduled for November 2026.
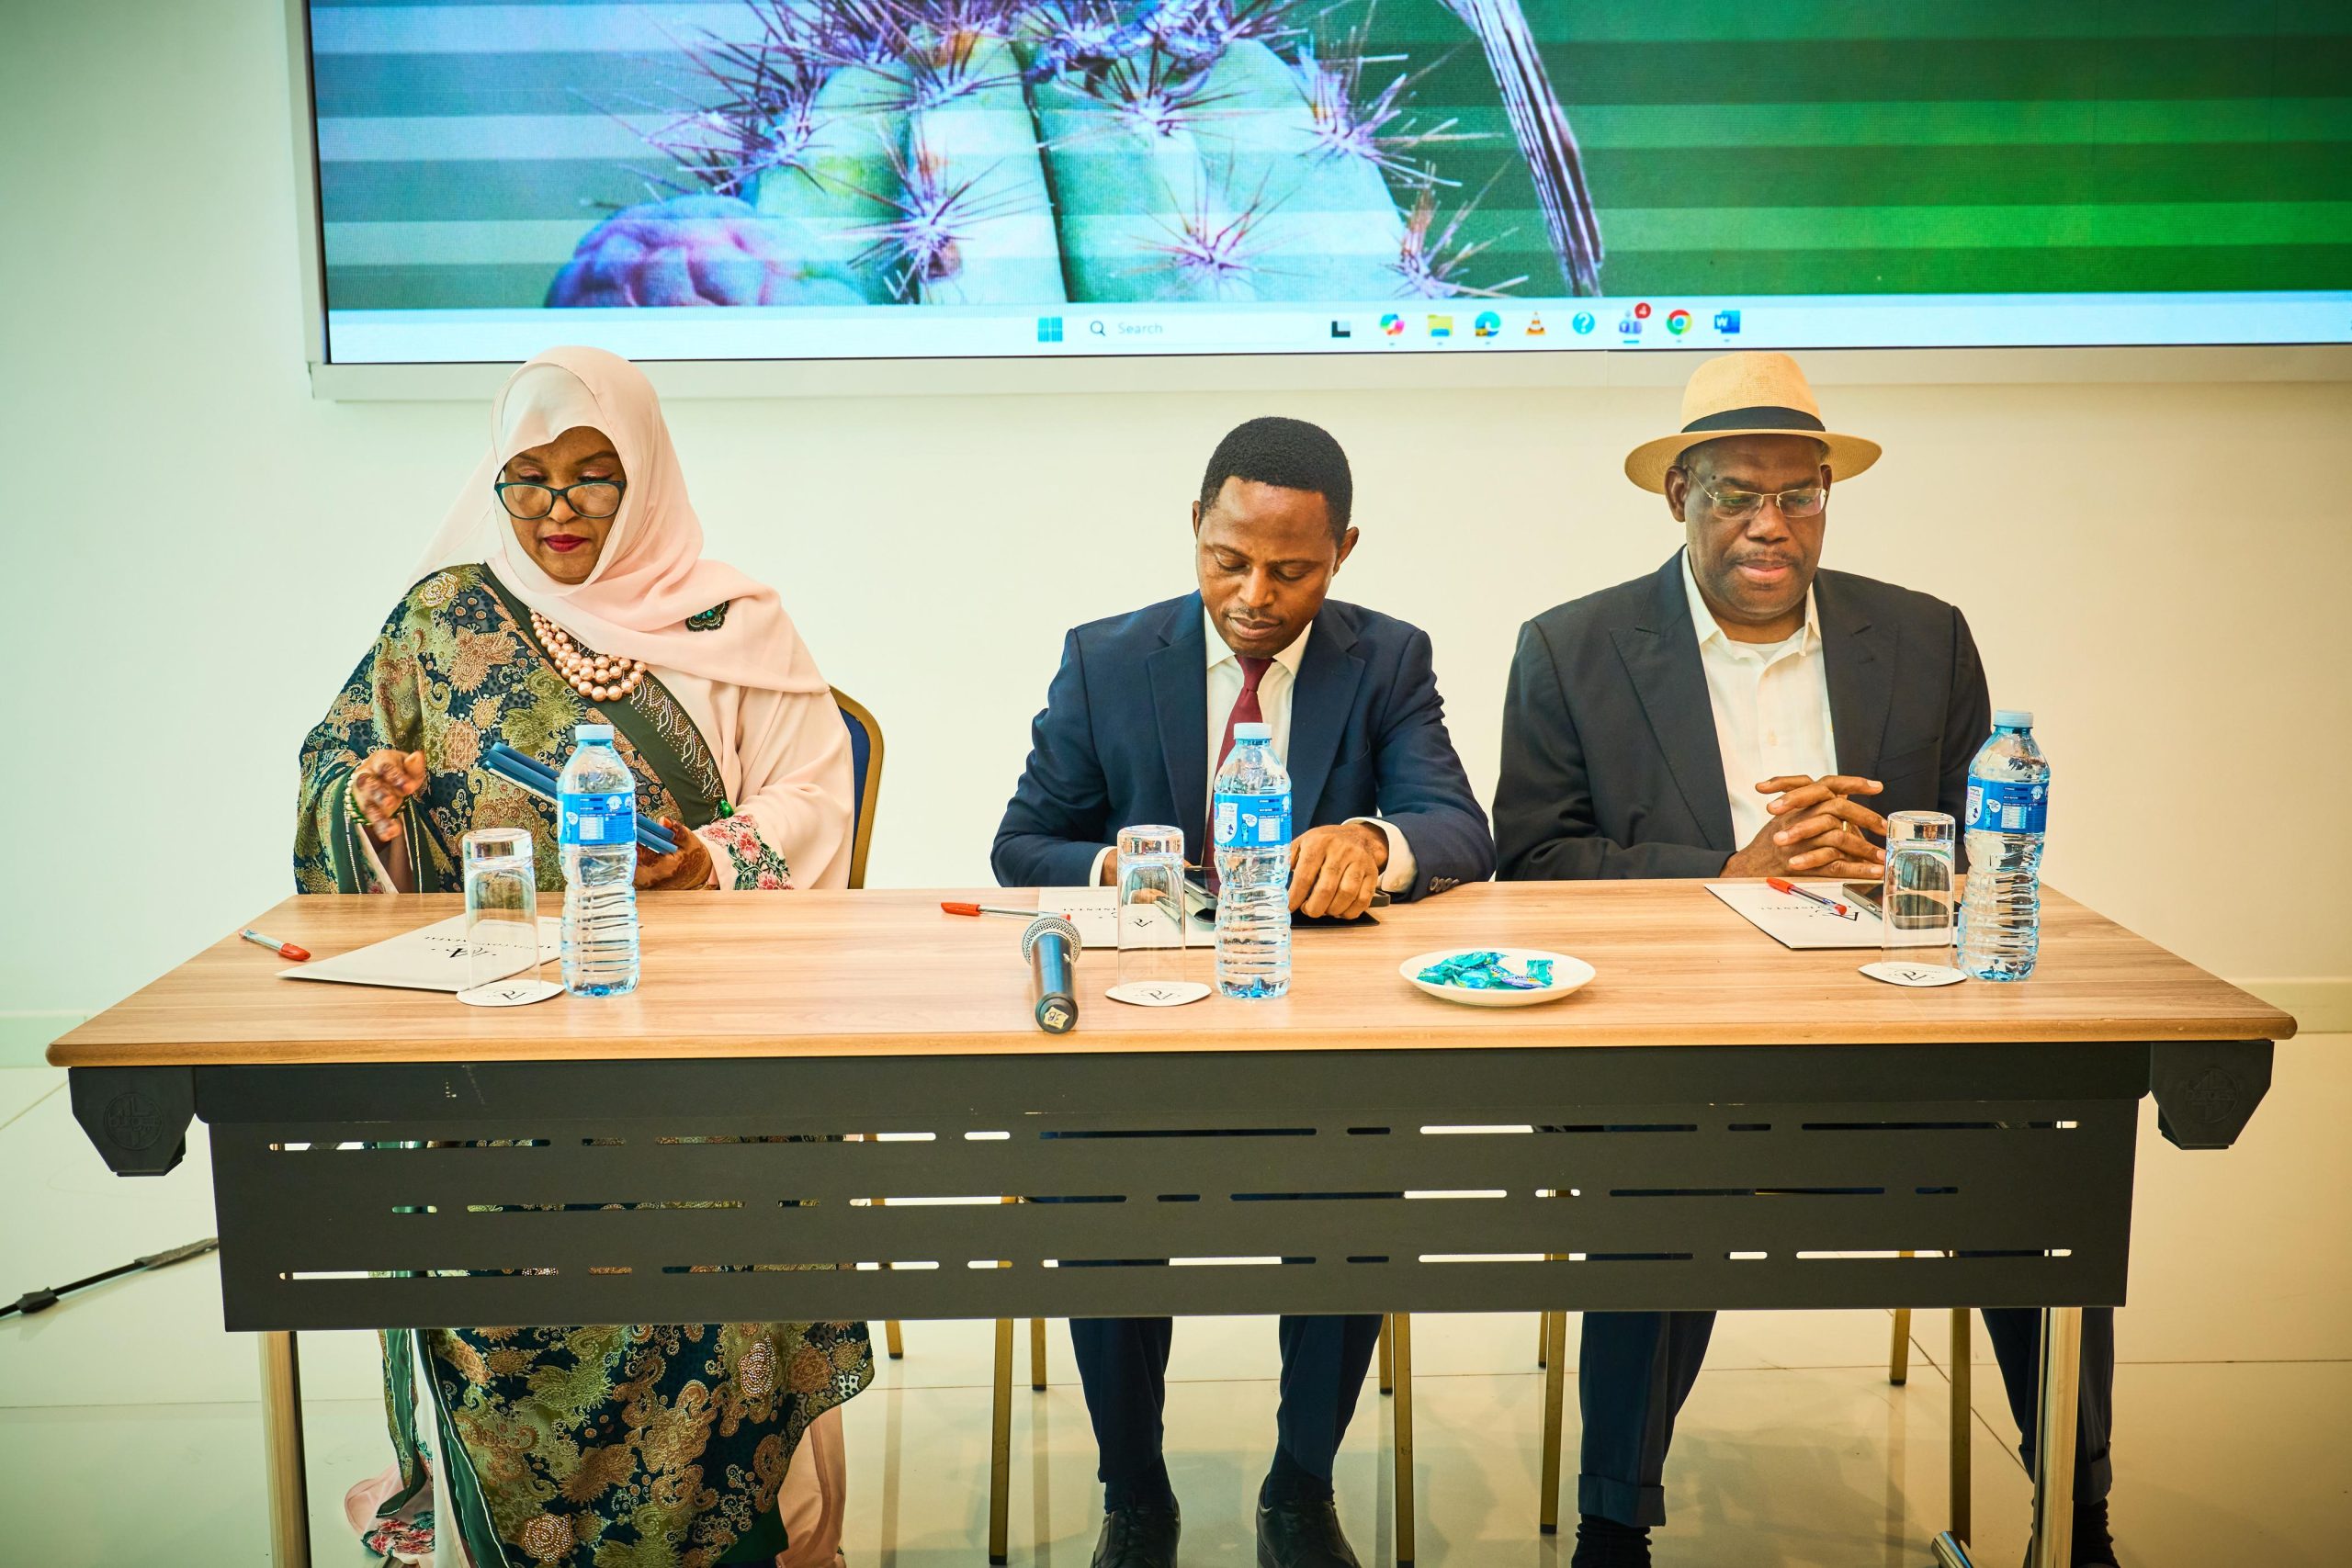
A statement by NFIU quoted Chief Executive Officer Hafsat Abubakar Bakari, saying that, Nigeria must demonstrate not only the strength of its laws and institutional frameworks but also their effectiveness in practice.
Bakari said the initiative builds on Nigeria’s successful exit from the Financial Action Task Force (FATF) Grey List in October 2025, underscoring the country’s commitment to protecting the integrity of its financial system.
She stressed that Nigeria must be able to provide evidence of the results achieved through its laws, policies and institutional arrangements, rather than merely describing the frameworks in place.
Representing the Director-General of GIABA, Giwa Siman Sechap, Director of Evaluations and Compliance at the GIABA Secretariat, said mutual evaluation was a collective national responsibility requiring effective coordination among relevant institutions.
He noted that countries undergoing assessment must demonstrate both technical compliance with international standards and the effectiveness of measures implemented to combat financial crimes.
According to him, the training would strengthen participants’ knowledge, coordination and readiness to present credible, evidence-based accounts of Nigeria’s efforts.
Similarly, SecFIN Africa’s Country Representative, Professor Shehu Abdullahi, said effective preparation required sustained capacity development, reliable information-sharing and collective ownership of national priorities.
He said the exercise would help Nigeria identify gaps, consolidate existing progress and demonstrate the effectiveness of its financial integrity framework.
The programme brings together representatives of more than 20 institutions involved in financial intelligence, regulation, law enforcement, prosecution, asset recovery, border control, revenue administration and national security.
Participating agencies include the Central Bank of Nigeria, Economic and Financial Crimes Commission, Department of State Services, Independent Corrupt Practices and Other Related Offences Commission, Federal Ministry of Justice, Nigeria Police Force, Nigeria Customs Service, Nigeria Revenue Service and National Drug Law Enforcement Agency.
Others are the Corporate Affairs Commission, Securities and Exchange Commission, National Insurance Commission, Nigerian Financial Intelligence Unit, National Counter Terrorism Centre, Bureau of Public Procurement, Code of Conduct Bureau, Nigeria Extractive Industries Transparency Initiative and Special Control Unit Against Money Laundering, among others.
Their participation is expected to strengthen coordination and demonstrate how Nigeria’s AML/CFT/CPF framework delivers measurable results across relevant sectors.
The NFIU disclosed that Nigeria had increased its pool of accredited global experts on FATF standards from fewer than 10 to 25 over the past two years.
It said the current training forms part of a broader capacity-building programme under which additional cohorts of between 100 and 150 participants are expected to be trained quarterly, with possible future expansion to the private sector.
The sessions will cover financial intelligence, regulatory supervision, virtual assets, beneficial ownership transparency, investigations and prosecutions, asset confiscation, international cooperation, targeted financial sanctions and proliferation financing risks.
Participants will also undertake practical exercises and simulated assessment interviews to prepare them to respond to evaluators’ questions with accurate information and verifiable evidence.
The programme builds on a national stocktake and gap analysis coordinated by the NFIU, with support from the EFCC, DSS, ICPC, CBN, NAICOM and SEC through the Inter-Ministerial Committee.
The exercise assesses the implementation of existing measures, identifies strengths and outstanding gaps, and establishes priorities for corrective action. It also provides a common basis for aligning national preparations with the responsibilities and contributions of participating institutions.
Bakari said the ultimate objective was to translate the collaborative effort into measurable improvements in the country’s capacity to detect and disrupt financial crimes.
She added that coordinated action, evidence-based assessment and clearly defined institutional responsibilities would help build a stronger and more effective financial integrity system.
The initiative forms part of Nigeria’s broader efforts to sustain inter-agency collaboration, strengthen institutional capacity and demonstrate progress ahead of its forthcoming mutual evaluation.
